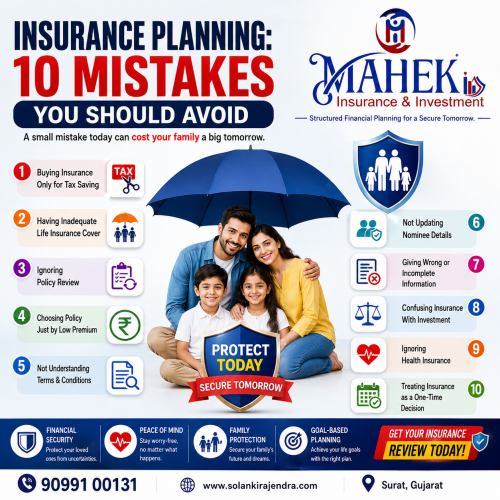
Insurance Planning એટલે માત્ર policy ખરીદવી નહીં, પરંતુ તમારી આવક, પરિવારની જવાબદારી, લોન, બાળકોના ભવિષ્ય અને retirement goalsને ધ્યાનમાં રાખીને યોગ્ય financial protection ગોઠવવી.
ઘણા લોકો insurance ત્યારે લે છે જ્યારે કોઈ agent સમજાવે, tax saving માટે લે છે અથવા માત્ર premium જોઈને નિર્ણય કરે છે. પરંતુ યોગ્ય insurance planning માટે થોડું વધુ વિચારવું જરૂરી છે.
1. માત્ર Tax Saving માટે Insurance લેવું
ઘણા લોકો financial yearના અંતે tax saving માટે ઝડપથી insurance policy ખરીદી લે છે.
પરંતુ insuranceનો મુખ્ય હેતુ financial protection છે, માત્ર tax saving નહીં.
શું કરવું?
પહેલા તમારી protection requirement સમજો અને પછી tax benefitને એક factor તરીકે જુઓ.
2. પરિવારની જરૂરિયાત કરતાં ઓછું Insurance Cover રાખવું
કેટલીક વાર વ્યક્તિ પાસે insurance હોય છે, પરંતુ પરિવાર માટે જરૂરી cover કરતાં ઘણું ઓછું હોય છે.
તમારા મૃત્યુ પછી પરિવારને:
- ઘરખર્ચ
- બાળકોનું શિક્ષણ
- લોન
- પરિવારની અન્ય જવાબદારીઓ
માટે મોટી રકમની જરૂર પડી શકે છે.
શું કરવું?
તમારી income, liabilities અને future goals પ્રમાણે insurance requirementનું review કરો.
3. Policy ખરીદીને પછી ભૂલી જવું
Insurance policy ખરીદ્યા પછી ઘણા લોકો તેને વર્ષો સુધી review કરતા નથી.
પરંતુ જીવનમાં ઘણી બાબતો બદલાય છે:
- Income વધે છે
- Marriage થાય છે
- બાળકો થાય છે
- Home loan આવે છે
- Business expand થાય છે
- Retirement નજીક આવે છે
એટલે insurance planning પણ બદલાતી જરૂરિયાત પ્રમાણે update થવી જોઈએ.
4. માત્ર Premium જોઈને Policy પસંદ કરવી
“આ policyનો premium ઓછો છે” — માત્ર આ કારણસર policy પસંદ કરવી યોગ્ય નથી.
તમારે જોવું જોઈએ:
- Coverage કેટલું છે?
- Policy term શું છે?
- Benefits શું છે?
- Premium payment term શું છે?
- Conditions અને exclusions શું છે?
- Policy તમારા financial goals સાથે match થાય છે કે નહીં?
Low premium હંમેશા best policy હોતી નથી.
5. Policyના Terms & Conditions ન વાંચવા
Insurance contract એક મહત્વપૂર્ણ financial document છે.
Policy લેતા પહેલાં તેના:
- Benefits
- Exclusions
- Premium payment conditions
- Claim-related requirements
- Policy servicing rules
સમજવા જરૂરી છે.
કોઈ બાબત સમજાતી ન હોય તો advisor પાસે સ્પષ્ટતા માંગવી જોઈએ.
6. Nominee Update ન કરવો
Nomination ખૂબ મહત્વનું છે.
Marriage, children અથવા family circumstances બદલાયા પછી nominee details પણ review કરવી જોઈએ.
શું કરવું?
તમારી policyમાં nominee details યોગ્ય છે કે નહીં તે સમયાંતરે check કરો.
7. Health અને Lifestyle વિશે ખોટી માહિતી આપવી
Insurance proposal ભરતી વખતે health, smoking, medical history અને અન્ય જરૂરી માહિતી સાચી અને સંપૂર્ણ આપવી ખૂબ મહત્વપૂર્ણ છે.
માહિતી છુપાવવાથી ભવિષ્યમાં claim સમયે સમસ્યા ઊભી થઈ શકે છે.
Golden Rule:
Insurance applicationમાં “Honesty is the best policy.”
8. Life Insurance અને Investmentને એક જ વસ્તુ માનવી
Life insuranceનો મુખ્ય હેતુ financial protection છે.
Investmentનો હેતુ wealth creation હોઈ શકે છે.
કેટલાક insurance productsમાં savings/investment component પણ હોય છે, પરંતુ policy પસંદ કરતી વખતે પહેલા એ સમજવું જરૂરી છે કે તમારી મુખ્ય જરૂરિયાત શું છે:
Protection?
Savings?
Retirement income?
Child education?
Wealth creation?
તમારા goal પ્રમાણે યોગ્ય financial strategy બનાવવી જોઈએ.
9. Health Insuranceને Ignore કરવું
ઘણા લોકો પાસે life insurance હોય છે પરંતુ health insurance પૂરતું નથી.
Medical expenses ઝડપથી વધી શકે છે અને મોટી hospitalization familyની savings પર અસર કરી શકે છે.
એટલે overall financial planningમાં health insurance અને life insurance બંનેનું સ્થાન અલગ છે.
10. Insurance Planningને “One-Time Decision” માનવું
સૌથી મોટી ભૂલ એ છે કે:
