SIP vs. Traditional Savings for Child Education Goals
Meta Title: SIP vs Traditional Savings for Child Education: Which Is Better?
Meta Description: Planning for your child’s education? Understand the difference between SIP and traditional savings, their benefits, risks, and how to choose an approach based on your education goal and time horizon.
SIP vs. Traditional Savings for Education Goals: Which One Should Parents Choose?
Every parent wants to give their child the best possible education. But education costs can rise significantly over the years, making early financial planning important.
Many parents face a common question:
Should I simply save money every month, or should I invest through a SIP for my child’s education?
The answer depends on your goal amount, time horizon, risk tolerance and financial situation. SIP and traditional savings are not exactly the same—they serve different purposes.
What Is Traditional Savings?
Traditional savings generally means keeping money in options such as:
- Savings accounts
- Recurring deposits
- Fixed deposits
- Other relatively conservative savings instruments
The key attraction is predictability and relatively lower market risk.
For parents who have a short-term education requirement or need higher certainty around the money, conservative savings can have an important role.
However, when the education goal is 10–15 years away, parents should also consider whether their savings strategy has enough potential to keep pace with rising education costs.
What Is SIP?
A Systematic Investment Plan (SIP) is a method of investing a fixed amount periodically, usually monthly, into a mutual fund scheme. AMFI describes SIP as a way to invest regularly and notes that it can encourage disciplined investing and rupee-cost averaging.
For example, instead of waiting until your child reaches college age, you could invest a fixed amount every month toward the education goal.
The important point is that SIP is an investment method, not a guaranteed-return product. The risk and return depend on the mutual fund scheme selected. Mutual fund investments are subject to market risk and returns are not guaranteed.
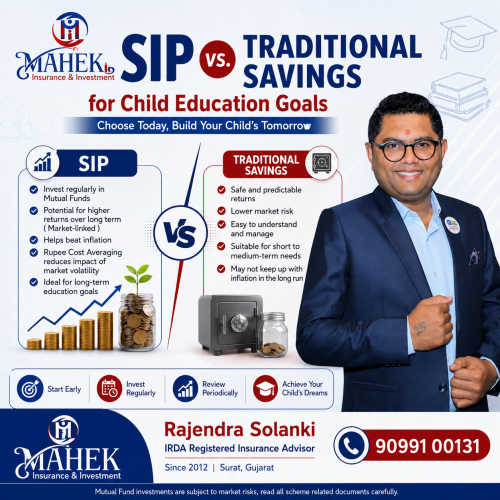
SIP vs. Traditional Savings
| Factor | SIP | Traditional Savings |
|---|---|---|
| Investment style | Regular investment in mutual funds | Saving/depositing money |
| Market exposure | Depends on the chosen fund | Generally lower market exposure |
| Return potential | Market-linked | Generally more predictable |
| Risk | Can be moderate to high depending on scheme | Generally lower |
| Suitable horizon | Particularly useful for long-term goals | Useful for short/medium-term needs |
| Inflation protection | Potentially better over long periods, but not guaranteed | May be limited depending on the interest rate |
| Discipline | Monthly automated investing can help | Regular deposits can also create discipline |
| Guarantee | No guaranteed return | Depends on the specific savings product |
SEBI and AMFI emphasize that investors should understand the risks and choose investments according to their objectives and risk appetite.
Why Time Matters in Child Education Planning
Suppose your child is currently 5 years old and you expect higher education at age 18.
You have approximately 13 years to prepare.
That time can be valuable because a long investment horizon may allow you to build the education corpus gradually rather than trying to arrange a large amount at the last moment.
SEBI's investor education material also highlights SIP as a regular investment approach intended for longer-term capital appreciation and saving discipline.
The key principle:
Start early → invest regularly → review periodically → gradually align risk as the goal approaches.
Don't Forget Education Inflation
One of the biggest mistakes parents make is calculating today's education cost and assuming the same amount will be sufficient in the future.
For example:
Today's estimated education cost: ₹20 lakh
Time available: 12 years
The actual amount required in the future could be considerably higher because education expenses may increase over time.
Therefore, education planning should begin with the future education corpus, rather than simply today's cost.
Is SIP Always Better?
No.
It would be incorrect to say that SIP is always better than traditional savings.
SIP investments, particularly equity-oriented mutual funds, are market-linked. Their value can rise and fall, and there is a possibility of loss of principal.
For a long-term education goal, a market-linked investment approach may have a role, but the investment strategy should be based on:
- Years remaining until the education goal
- Required future corpus
- Monthly investment capacity
- Risk tolerance
- Existing investments
- Other family financial goals
As the education goal gets closer, parents should also review whether the portfolio's risk level remains appropriate.
A Better Approach: Goal-Based Education Planning
Instead of asking only:
“SIP કરું કે Savings?”
ask:
“મારા બાળકના Education Goal માટે કેટલું Corpus જોઈએ અને તે Corpus ક્યારે જોઈએ?”
A structured education plan can follow these steps:
1. 🎯 Define the Education Goal
Identify the likely course, college type and expected future cost.
2. 📊 Calculate the Future Corpus
Estimate how much money may be required when the child reaches college age.
3. 💰 Determine the Monthly Investment
Work backward from the target corpus and available time.
4. 📈 Choose the Appropriate Investment Mix
Select investments based on the goal's time horizon and your risk profile—not simply because a particular investment has performed well recently.
5. 🔄 Review the Plan Regularly
Income, expenses, education costs and investment values can change. Regular reviews help keep the plan aligned with the goal. SEBI also recommends periodically reviewing financial goals and portfolios.
The Biggest Advantage Is Not SIP or Savings—It's Starting Early
Parents often wait for their income to increase before starting education planning.
But waiting can make the required monthly contribution much higher later.
Early planning gives you more time to build the corpus gradually.
So the real comparison isn't simply:
SIP vs. Savings
It is:
Unplanned Saving vs. Goal-Based Financial Planning.
Final Thoughts
For a child's education goal, traditional savings and SIP can both have a place, depending on the family's needs.
Traditional savings can provide stability and may be appropriate for money needed in the near term.
SIP can provide a disciplined way to invest regularly toward long-term goals, but because mutual funds are market-linked, they come with investment risk and no guaranteed returns.
The right strategy should therefore be based on the education goal, time horizon, risk profile and overall family financial plan.
At MAHEK INSURANCE & INVESTMENT
We help families think beyond simply “saving money” and focus on structured Child Education Planning—estimating the future education requirement, understanding the time available and creating a disciplined financial roadmap.
Because your child's education goal deserves a plan—not just a savings account.
MAHEK INSURANCE & INVESTMENT
Rajendra Solanki
IRDA Registered Insurance Advisor
Since 2012 | Surat, Gujarat
